

Ria Money Transfer
by Ria Money Transfer (Ria Financial)
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
Sending money abroad is one of those jobs that looks simple until a real deadline appears. A relative needs help with a bill, someone is waiting for money in another country, or I need to transfer funds without visiting a branch. In those moments, I want a service that explains the process clearly and lets me keep track of what I am doing. Ria Money Transfer is built for that specific task, and after using it, I found it most useful when international transfers need to fit into an ordinary household routine rather than become a separate errand.
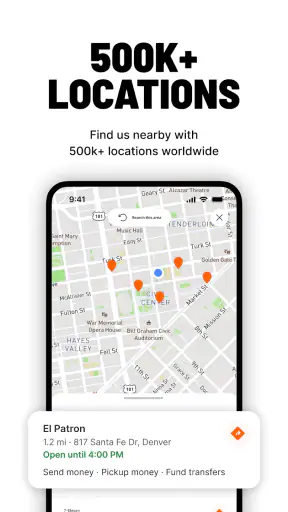
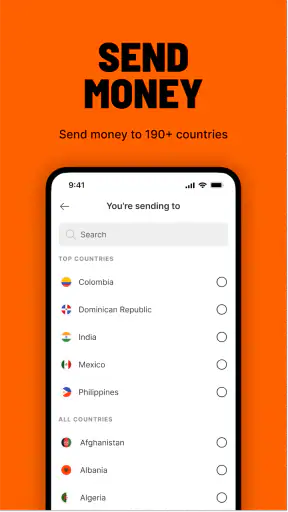
This is a free finance app from Ria Money Transfer, also known as Ria Financial. Its main purpose is sending money to Mexico, India, and more than 190 countries. The app has been available since December 29, 2017, and its current release is version 3.101.0 for devices running Android 8.0 or later. It is rated for Everyone, although that broad age label should not be confused with independent access to financial decisions.
How Ria fits into a shared household routine
I can easily imagine using it on a shared family tablet or a phone that several people rely on for household administration. One person may collect the recipient’s details, another may check the amount, and the person who actually owns the payment method may complete the transfer. That division sounds practical, but it also creates a boundary that matters: the app can help a household coordinate a transfer, yet the responsibility for checking the details and authorizing the payment should stay with the adult account holder.
A realistic example would be a family in the United States sending support to a parent in Mexico. I might open the app while discussing the amount with my partner, confirm the recipient’s name and destination, and then pause before payment so we can compare the information together. This is where the mobile format helps. I do not have to move between a website, a branch, and a messaging app just to organize the basic task.
That convenience does not mean I would leave the app permanently signed in on a device used by children or guests. A shared device changes the risk profile of any finance tool. Even if someone only intends to “look,” saved sessions, notifications, recipient information, or transaction details can expose more than expected. My practical rule is simple: use a shared screen for discussion if necessary, but keep the final review and authorization in the hands of the person responsible for the money.
The app is also better suited to deliberate transfers than to casual experimentation. I would not ask a child to explore its screens as if it were a general family app, and I would not treat a teenager’s device as an appropriate place to store an adult’s financial session. The Everyone content rating describes the app’s general suitability, not the maturity needed to send money responsibly.
Setting it up without blurring account boundaries
The first useful habit is to decide who the account belongs to before installing anything. In a household, that may be the person who regularly sends international support, or the adult who manages shared finances. The app can be discussed by several people, but I would avoid treating one login as a communal profile. A clear owner makes it easier to know who should verify the recipient, review the transfer, and deal with any follow-up.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
During setup, I would keep the process focused and avoid rushing through names or destination details. International transfers are especially unforgiving of small mistakes because the recipient may be far away and the correction process can become inconvenient. My non-obvious tip is to ask the recipient to send their details in a consistent written format before starting. That reduces the chance that one family member reads a name aloud while another types an approximation.
I would also prepare the transfer conversation before opening the payment screen. The sender should know the intended amount, the country, the recipient, and who will be responsible for confirming receipt. This sounds basic, but it prevents a common household problem: one person assumes another has checked the details, while nobody has actually done it.
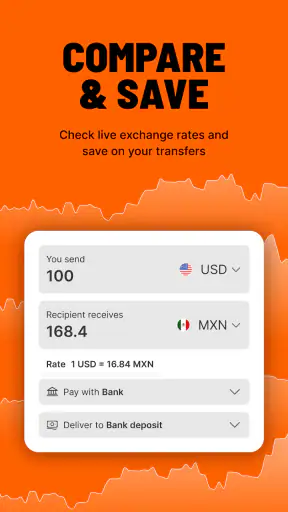
Because the app is free to install, it is easy to mistake the absence of an upfront app charge for the total cost of sending money. I would always review the transfer details shown during the process, including the amount being sent and the amount expected by the recipient, before confirming. Exchange rates and transfer costs are part of the decision, so the important number is not only what leaves the sender’s side but also what the other person receives.
That comparison is one area where Ria has to be judged against the usual alternatives. A bank transfer may feel more familiar for recurring payments, especially when both sides already use the same banking network, but it can be less convenient for a family that needs a dedicated international remittance service. A digital wallet may be faster for people already inside the same platform, while a cash-oriented service can be more useful for recipients who do not depend on a bank account. Ria’s appeal is its international-transfer focus, not the promise that it is automatically the cheapest or best route for every corridor.
Coordinating a transfer when more than one person is involved
For shared household use, I would separate coordination from authorization. Someone can help gather the information, translate a screen, or check that the destination country is correct. The account holder should still make the final decision. This arrangement is particularly useful when an older relative is comfortable speaking about the transfer but less comfortable navigating a mobile interface.
My preferred workflow is to create a short checklist outside the payment step: recipient identity, destination, amount, purpose, and the person who will confirm delivery. I would then read each item again on the final review screen. The extra minute is worthwhile because a transfer is not like editing a normal message after sending it. The recipient’s details deserve a separate pause rather than a quick tap while talking to someone else.
Another useful practice is to keep household conversations away from assumptions about timing. A sender may think “sent” means “available immediately,” while the recipient may interpret it as a promise that the money can already be collected or used. I would tell the recipient when the transfer has been initiated, then wait for confirmation before treating the matter as complete. The app helps organize the sending side, but communication with the recipient remains essential.
I also would not use a screenshot as the only record of a transfer. A screenshot can be useful for sharing basic reference information, but it may reveal personal or financial details if forwarded carelessly. I prefer sending only what the recipient needs and keeping the fuller transaction information private. On a shared device, this matters even more because photos, notifications, and recent files can be visible to other users.
The app’s scale suggests that it is not a niche experiment. It has more than 10 million installs, with an average rating of 4.8 from around 264 thousand ratings and roughly 11 thousand written reviews. Those figures make me more comfortable treating it as an established option, but they do not remove the need to judge the specific transfer route. A strong overall reputation cannot guarantee that every destination, payment method, or household situation will feel equally smooth.
Trust, age, and the person who controls the payment
The age rating of Everyone makes the app appear approachable, and the interface is intended for ordinary users rather than financial professionals. Still, sending money is an adult responsibility in practice. I would be comfortable showing a young person how international transfers are organized, but I would not give them unsupervised control of an account or payment method simply because the app itself is broadly age-rated.
This distinction is important in families with teenagers. A teenager might help a parent read instructions, compare the recipient’s spelling, or explain a screen. That can be a positive shared task. It should not become an informal arrangement where the teenager stores credentials, approves transfers, or becomes the only person who understands what happened. Good coordination means knowledge is shared while authorization stays clearly assigned.
The same applies when helping an older family member. I would sit beside them, let them see each stage, and ask them to confirm the final information themselves. Taking over completely may be faster, but it makes future use harder and can create uncertainty about who actually initiated a transfer. Ria works best in this context as a tool that supports a conversation, not as a substitute for one.
Trust also includes checking the recipient through a separate channel. If a message suddenly requests money to a different person or country, I would verify it by calling the intended contact directly rather than relying on the message thread that started the request. No transfer app can decide whether a family emergency is genuine. The app can process the instruction, but the household must validate the reason behind it.
For that reason, I would skip Ria for a child’s independent allowance system, a shared household fund with no clear manager, or any arrangement where several people expect to use one account casually. It is also not my first choice when a bank transfer already provides a simpler, familiar route between the sender and recipient. The dedicated remittance focus is valuable, but it does not automatically solve account ownership or family governance.
Where the app feels strong, and where I would slow down
The strongest part of the experience is its focus. I am not opening a general banking dashboard and searching through unrelated tools; I am using a service designed around sending money internationally. That focus makes sense for people who regularly support relatives abroad, pay someone in another country, or need a recognizable remittance workflow on a phone.
The country coverage is another meaningful advantage. Supporting Mexico, India, and more than 190 countries gives the app a broad reach for households whose relatives or obligations are spread across borders. However, broad coverage should not be read as identical service everywhere. The practical details can vary by destination, so I would inspect the specific route before promising a recipient exactly how and when the money will arrive.
The main friction is the responsibility placed on the sender. I still need to understand the displayed cost, exchange result, recipient information, and delivery expectations. Someone looking for a completely automatic “send and forget” experience may find that the app does not remove enough decision-making. That is not necessarily a flaw in a money-transfer service, but it does mean the app rewards careful use more than hurried use.
Compared with visiting a physical remittance location, the app is more convenient for preparation and repeat use. I can organize the transfer from home and involve another household member without arranging a trip. A branch may be preferable for someone who wants face-to-face assistance or does not feel comfortable entering financial details on a phone. Compared with a bank, Ria is more directly centered on international remittances, while a bank may be the better choice for people who value all their financial activity in one established account.
Compared with a wallet-based service, Ria may make more sense when the recipient is not already tied to the same digital ecosystem. On the other hand, a wallet can be more natural for small, frequent payments between users who already know how it works. My choice would depend on the recipient’s access, the destination, the total cost, and whether the transfer is a one-off family payment or a repeated household obligation.
Who will benefit from using it
I would recommend this app to an adult who sends money across borders and wants a mobile-first way to manage the process. It is especially suitable for someone who values a dedicated remittance service, needs to send to a wide range of countries, and is willing to review the details rather than simply tap through them.
It can also work well for households that have a clear division of responsibilities. One person can help prepare the information, another can double-check it, and the account holder can authorize the payment. That arrangement turns a potentially stressful task into a small, repeatable routine. The key is that everyone knows which step belongs to them.
I would be more cautious recommending it to someone who rarely sends money internationally and already has an uncomplicated bank option. In that case, installing a separate service may add another account and another process without offering enough practical value. I would also hesitate if the recipient needs a very specific delivery method and the sender has not first checked whether that route suits them.
For people who are uncomfortable with financial apps, I would not describe Ria as a magic shortcut. The interface may make the transfer more accessible, but the user still needs to make informed choices. A trusted helper can improve the experience, provided the helper does not quietly take control of the account or payment decision.
My household verdict after using the app
Ria Money Transfer is a focused finance app that makes sense when international support is part of everyday family life. I like that it brings the task into a phone-based workflow and covers a large range of destinations. The free installation and broad availability lower the barrier to trying it, while its established presence and strong user reception make it a credible option to compare with banks, wallets, and in-person services.
My recommendation comes with a clear condition: treat it as a financial tool, not a casual shared-device app. Keep the account boundary clear, check the recipient details together when appropriate, and let only the responsible adult authorize the transfer. Those habits matter more than convenience when money is crossing borders.
The best reason to choose it is controlled convenience: it can make a recurring household responsibility easier without pretending that verification and communication are optional. If the recipient’s needs, destination, and payment route fit the service, I would consider using it. If a bank or wallet already handles the same transfer more simply, I would compare the final amount received before deciding. For careful senders, that balanced approach is where the app earns its place.
Overall, I see it as a practical choice for adults coordinating international transfers, including families that share the planning but not the financial authorization. I would recommend it to a friend who regularly sends money abroad and wants a dedicated mobile option, while reminding them to review every transfer as an individual financial decision.
Pros
- Send money to many countries through a widely recognized transfer network.
- Recipients can often choose cash pickup instead of using a bank account.
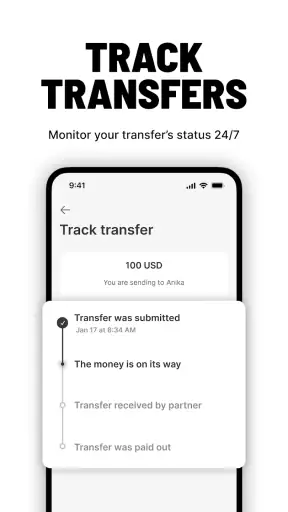
- Transfer tracking helps you monitor the status of an active transaction.
- Multiple payment methods may be available, depending on your location.
- The app provides exchange-rate and fee details before you confirm a transfer.
Cons
- Fees and exchange rates can vary significantly by destination and payment method.
- Identity verification may require personal documents before transfers are completed.
- Cash pickup availability depends on local agents and their opening hours.
- Some transfers may be delayed by compliance checks or recipient information errors.
- Transfer limits differ by country, account status, and selected delivery method.
FAQs for Ria Money Transfer
What is Ria Money Transfer, and how does it work?
Ria Money Transfer is an international remittance service that lets you send money to recipients in supported countries through its mobile app, website, or participating agent locations. Depending on the destination, the recipient may collect cash, receive funds in a bank account, or use another available delivery method. Before confirming a transfer, review the exchange rate, service fee, delivery estimate, and recipient information carefully.
Is Ria Money Transfer safe to use?
Ria uses account security measures, identity verification, transaction monitoring, and regulated money-transfer procedures to help protect customers and prevent fraud. However, no financial service is completely risk-free. Only send money to people you know, keep your login and verification codes private, and check the recipient’s details before paying. Ria may also request additional documentation for certain transfers or account activities.
How much does it cost to send money with Ria?
The total cost depends on several factors, including the sending country, destination, transfer amount, payment method, delivery option, and current exchange rate. Some transfers may have a visible service fee, while the exchange-rate margin can also affect the final amount received. The app normally displays the estimated fee, exchange rate, and recipient amount before you submit the transaction.
How long does a Ria Money Transfer take to arrive?
Delivery time varies according to the destination country, selected payout method, payment method, operating hours, weekends, holidays, and security checks. Cash-pickup transfers can sometimes be available quickly, while bank deposits or other delivery methods may take longer. The estimated arrival time shown in the app is not always guaranteed, so recipients should wait for confirmation before visiting an agent location.
What information do I need to send money through Ria?
You generally need a valid account, your personal details, a payment method, and accurate information about the recipient. Depending on the destination and transfer type, this may include the recipient’s full legal name, phone number, address, bank details, or identification information. Requirements can differ by country, and Ria may ask for identity documents or additional verification before completing the transfer.

Ria Money Transfer
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via us_support@riamoneytransfer.com, visit https://www.riamoneytransfer.com, or review their https://www.riamoneytransfer.com/en-us/privacy-policy/.










